London flex occupancy has held at 84%, according to the latest figures shared by the Workspace Intelligence Network (WIN). Total site revenue has also remained broadly flat despite new space opening. For a sector that is often asked to prove its staying power, that consistency matters.
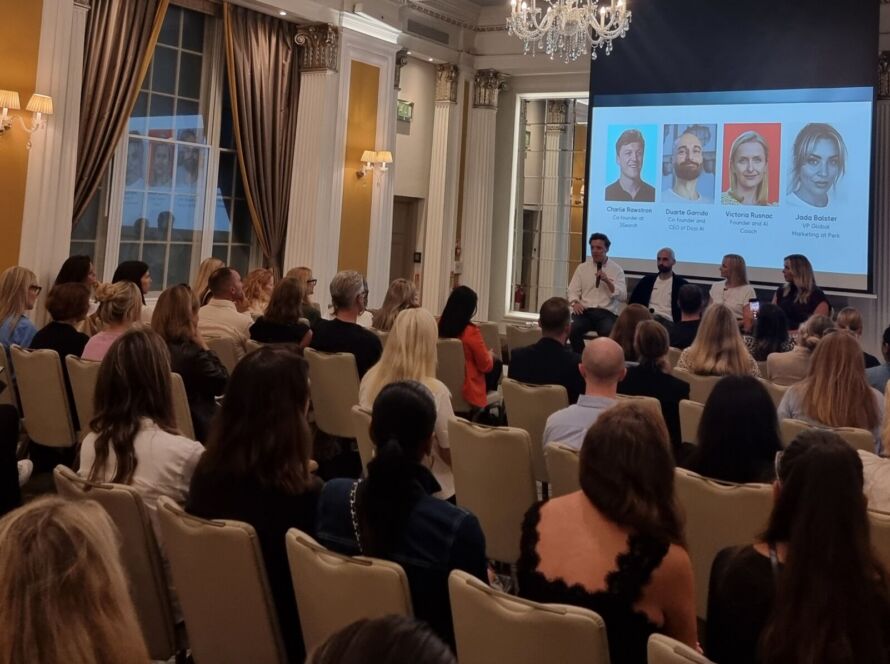
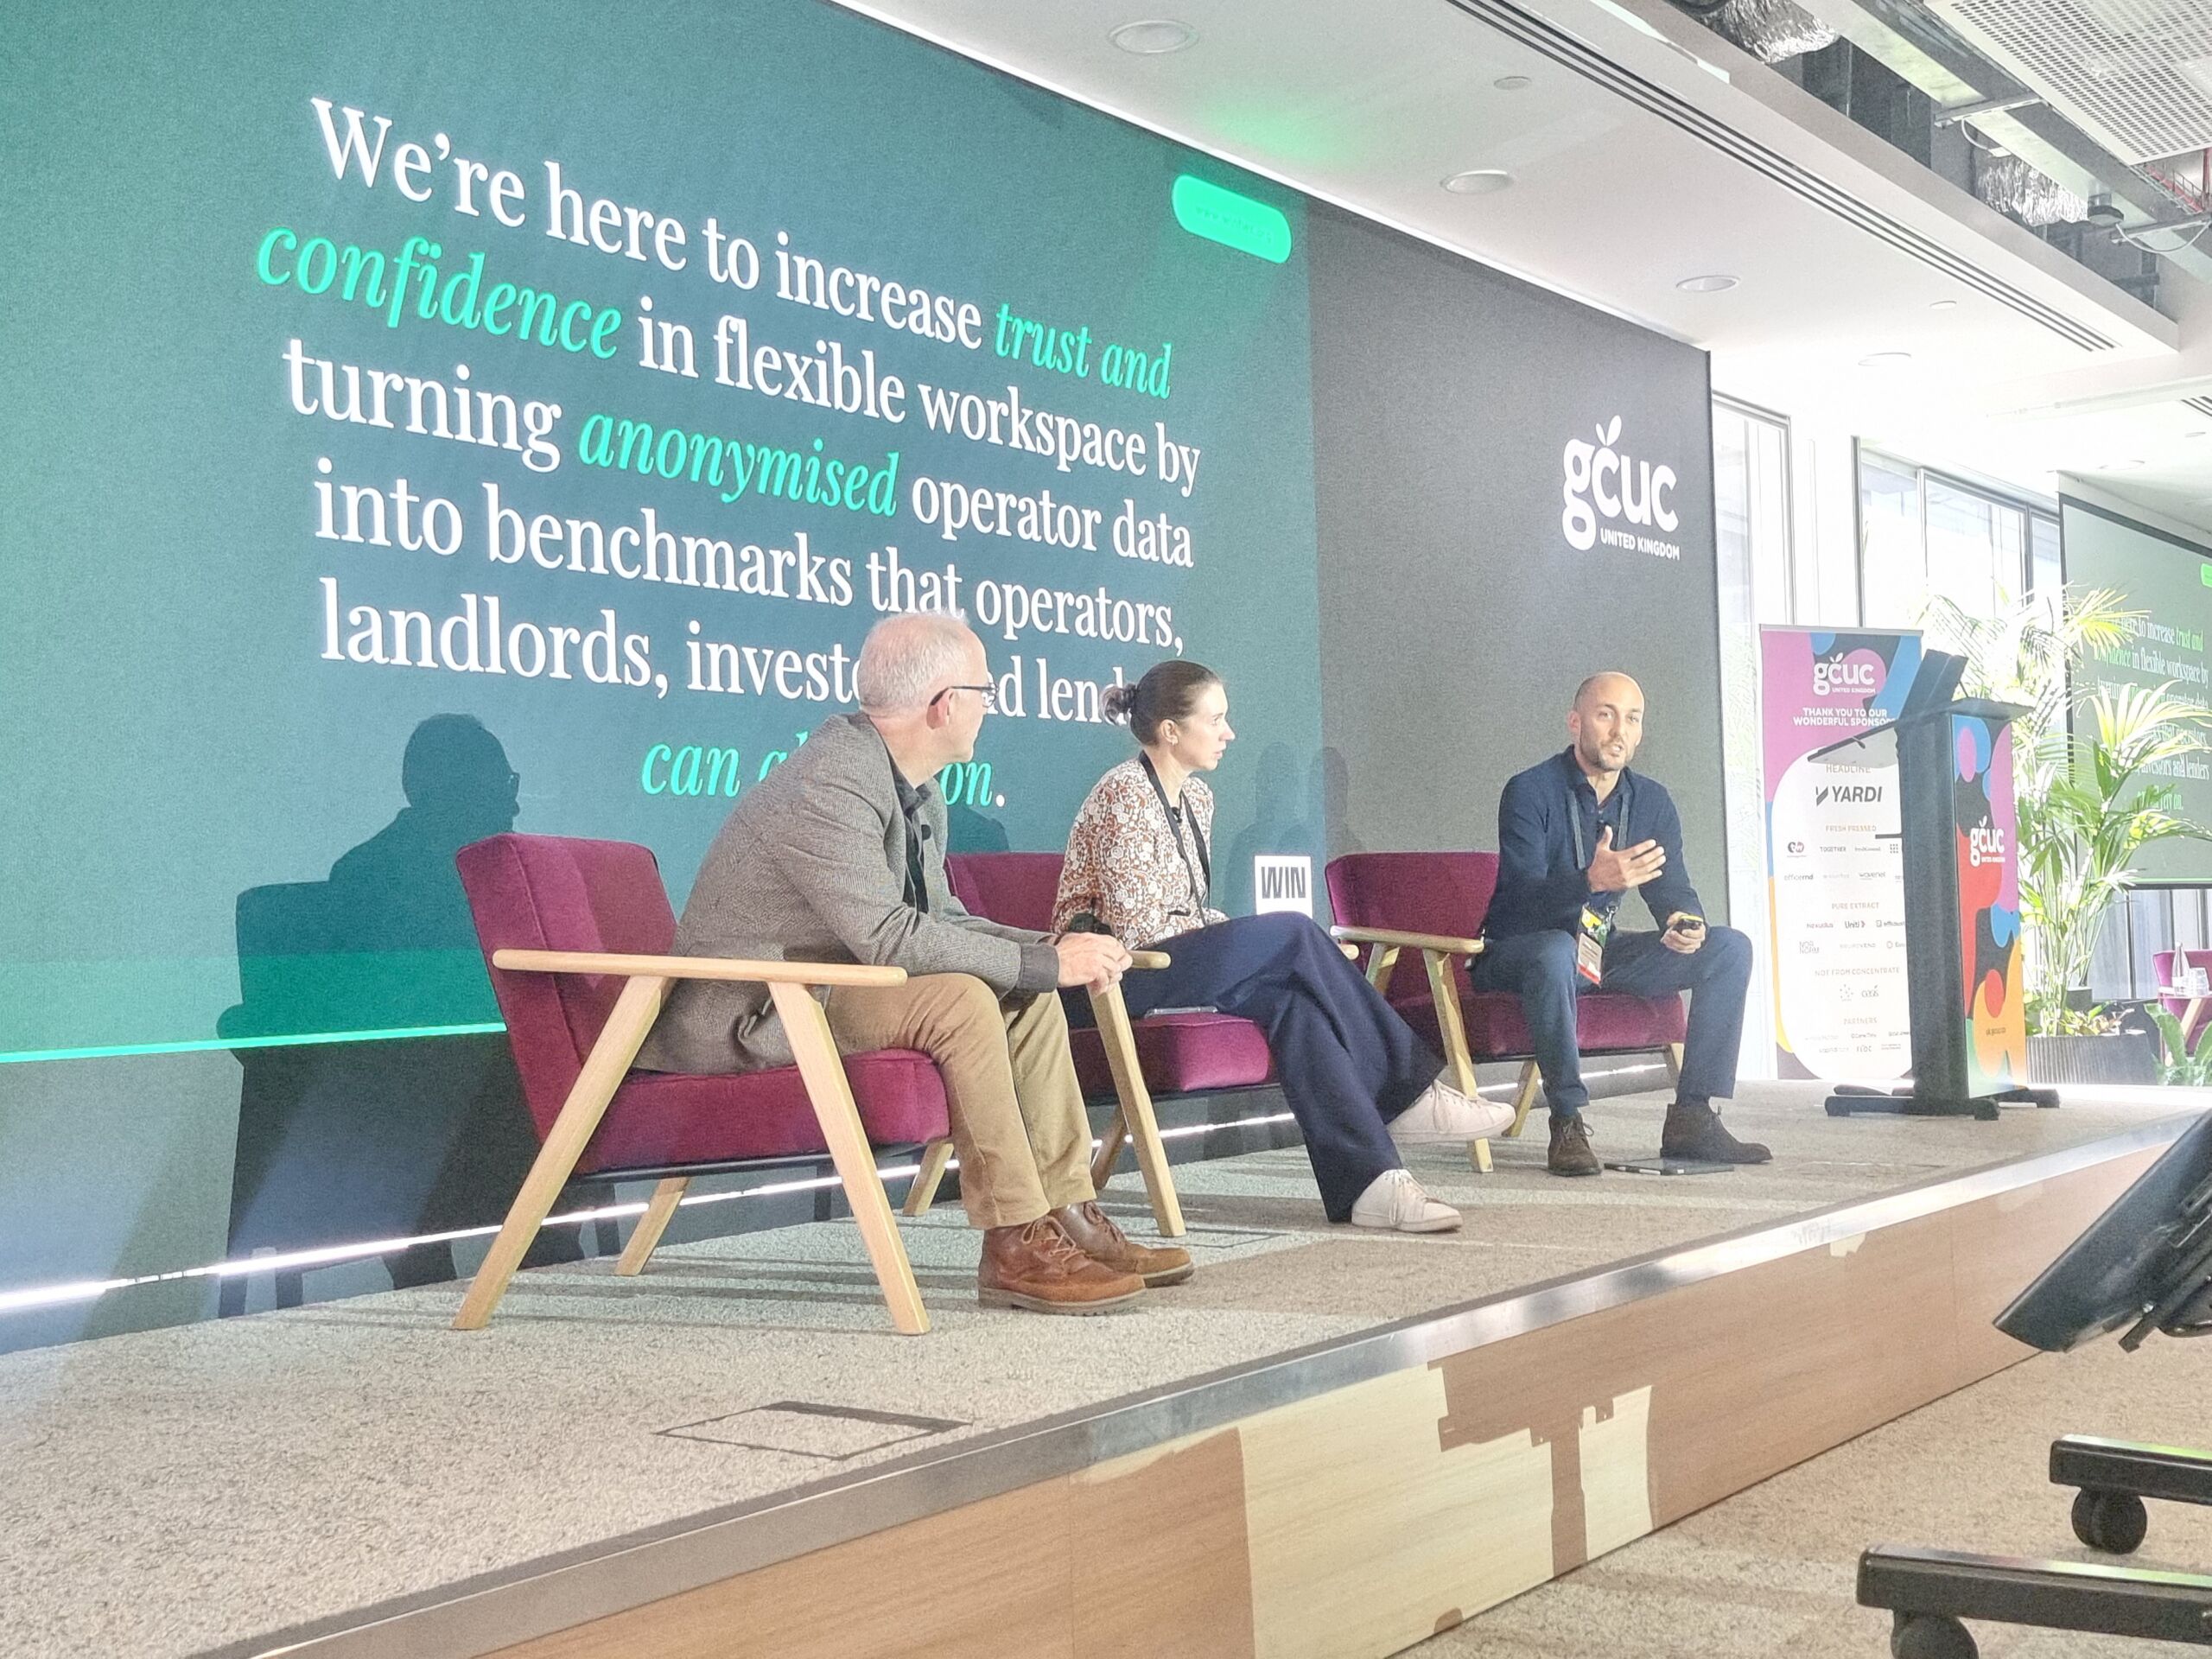
At WIN, A Year On: The State of Flex session at GCUC London on Thursday 8th October, Jonathan Bevan (Techspace), Jonny Rosenblatt (Spacemade) and Becky Gardiner (FORA) looked at both sides of the story: what the figures say about the market, and whether the sector is getting better at measuring itself.
A benchmark with more weight behind it
WIN is built around a straightforward idea. Operators share data, which is anonymised and returned as benchmarks they can use to compare performance with the wider market. It is owned by operators, for operators.
The network has grown from 26 to 42 members since last year’s GCUC UK and now covers more than 400 sites.
That scale makes the detail more valuable. Rather than relying on a single national figure, members can look at London sub-markets, major regional cities and broader regional comparisons. WIN has also developed a portal to make the results easier to use.
Resilience looks different when you can measure it
The London-wide occupancy figure is steady at around 84%, but the sub-market picture adds texture. The West End has remained above 84% occupancy for more than 15 months while achieving London’s highest rates. City Core occupancy has been rising while rates have held steady.
The point isn’t that every location performs the same way. It’s that operators can now test a claim about a location against a relevant benchmark.
That has immediate uses. Speakers described bringing the figures into board discussions, using them to underwrite new sites and putting building performance in context for landlord partners. A business plan is more convincing when its assumptions can be compared with what the market is actually delivering.
The next hurdle is speed
WIN’s progress has been substantial, but the session was open about the work still involved. Collecting data from members and returning useful results quickly is a challenge, particularly as the network grows.
A year on, WIN has done more than add members and sites. It is giving the flex sector a firmer basis for conversations with boards, landlords, investors and lenders. Congratulations to the WIN team and every operator contributing data. Building a credible picture of the market takes sustained effort, and this year’s progress shows what that collective effort can produce.